Personal Finance Tips for 2026: A Practical Money Playbook
The most useful personal finance tips are not about extreme frugality or complicated investment theory. They are small, repeatable decisions that protect your income and grow your savings over time. In 2026, with prices still shifting and interest rates in flux, a clear playbook matters more than ever. This guide walks you through the habits that actually change your bottom line.
I have coached people through layoffs, windfalls, and everything between, and the winners rarely have the highest incomes. They simply have systems. Below you will find the exact framework I use, plus the digital tools that make it automatic.
Start With a Spending Baseline
You cannot improve what you do not measure. Before chasing any strategy, spend thirty days tracking every dollar that leaves your account. The goal is awareness, not judgment.
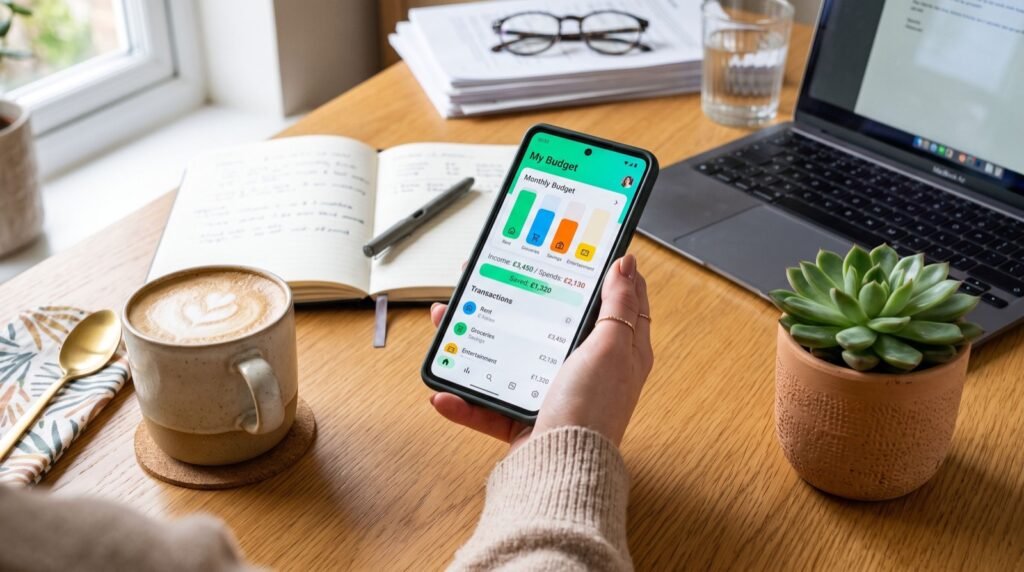
Most people discover two or three “leak” categories, often food delivery, unused subscriptions, and impulse shopping. Once those leaks are visible, plugging them feels obvious rather than painful. Linking your accounts to one of the leading money apps automates this tracking so you never miss a charge.
How much should you track before acting?
Thirty days captures most monthly bills and one full pay cycle. If your income is irregular, extend to sixty days so seasonal swings do not distort your baseline.
Build the 50/30/20 Framework
The 50/30/20 rule remains the most durable starting point for a reason: it is simple enough to stick with. Allocate 50 percent of take-home pay to needs, 30 percent to wants, and 20 percent to savings and debt payoff.
The table below shows how that split looks across common income levels in 2026. Treat it as a guide you can bend, not a rigid law.
| Monthly Take-Home | Needs (50%) | Wants (30%) | Save/Debt (20%) |
|---|---|---|---|
| $3,000 | $1,500 | $900 | $600 |
| $4,500 | $2,250 | $1,350 | $900 |
| $6,000 | $3,000 | $1,800 | $1,200 |
If your needs exceed 50 percent, you are not failing. It simply signals where to focus, whether that is negotiating rent, refinancing, or boosting income.
Personal Finance Tips That Compound Over Time
The strongest personal finance tips share one quality: they keep working while you sleep. Automation and consistency beat willpower every time. Put these on autopilot and watch the results stack up.
- Pay yourself first by auto-transferring savings on payday before you can spend it.
- Automate bill payments to kill late fees and protect your credit score.
- Raise your savings rate by one percent each quarter until it stings slightly.
- Review subscriptions every ninety days and cancel anything unused.
- Keep a buffer of one week of expenses in checking to avoid overdrafts.
An original insight from client work: tie each savings transfer to a named goal, such as “Japan 2027” rather than “savings.” People abandon generic accounts but rarely abandon a dream with a date attached.
Why your emergency fund comes first
Before investing aggressively, build a cushion of three to six months of expenses. The Consumer Financial Protection Bureau notes that even a small starter fund of a few hundred dollars dramatically reduces the odds of turning to high-interest debt during an emergency.
Tackle Debt With a Clear Order
Not all debt deserves equal urgency. High-interest credit card balances cost far more than a low-rate auto loan, so attack them first. Follow this sequence to free up cash fast.
- Make minimum payments on every account to stay current.
- Funnel extra cash toward the highest-interest balance, known as the avalanche method.
- Once a balance clears, roll that payment into the next debt.
- Celebrate each payoff to keep momentum, then redirect freed cash to investing.
When the numbers feel overwhelming, lean on reputable service experts or a certified counselor who can structure a plan around your situation.
Invest Early, Even in Small Amounts
Time in the market beats timing the market. Thanks to compounding, a modest monthly contribution started in 2026 can outpace a larger sum invested years later. Begin with tax-advantaged accounts before taxable ones.
For a plain-English primer on costs, risk, and account types, the investor education portal from FINRA is a trustworthy, jargon-light starting point.
Track Your Progress and Adjust Each Quarter
A budget is a living plan, not a one-time setup. Every three months, sit down and compare your actual numbers against your targets. This quarterly rhythm catches drift before it becomes a crisis.
During each review, ask three questions: Did my income change? Did any expense category creep upward? Am I on pace for my savings goal? Honest answers reveal exactly where to adjust, whether that means trimming a category or celebrating a win.
Life events deserve a mid-quarter review too. A raise, a new baby, a move, or a medical bill all reshape your numbers. Updating your plan promptly keeps small surprises from snowballing into debt. In my experience, the people who review quarterly save roughly twice as much over a year as those who set a budget once and forget it.
What is a realistic savings rate for 2026?
A 20 percent savings rate is the classic benchmark, but even 10 percent beats zero and builds momentum. Start where you can, raise the rate gradually, and let consistency do the heavy lifting rather than waiting for a perfect month that never arrives.
Frequently Asked Questions
What is the single most important personal finance tip?
Pay yourself first. Automating savings on payday guarantees you build wealth before lifestyle costs absorb every dollar.
How much should I keep in an emergency fund?
Aim for three to six months of essential expenses. Start with a 500 dollar buffer, then grow it gradually so unexpected bills never derail your budget.
Should I pay off debt or invest first?
Clear high-interest debt above roughly 8 percent before investing heavily, but always capture any employer retirement match first since that is an instant return.
Do budgeting apps really improve finances?
Yes, because visibility drives better choices. People who review spending weekly save more consistently and spot wasteful charges far sooner.
Your Next Move
These personal finance tips work because they remove friction and rely on systems instead of motivation. Track your spending, adopt the 50/30/20 framework, automate your savings, and invest early. Done consistently through 2026, these steps build real, lasting security.
Pick one tip to implement this week, set up the automation today, and explore trusted personal finance tips to keep your momentum going. Your future self will thank you.